
SECOND-HOME FINANCING
Vacation & Second Home Loans
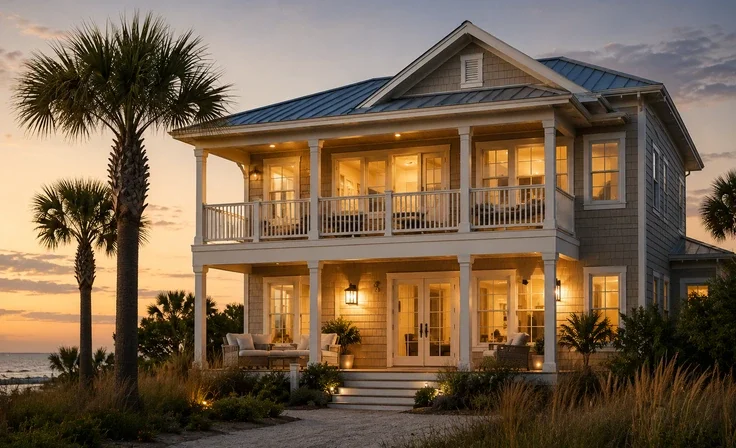
Finance a beach retreat, lake house, golf-course residence, or other eligible second home with a mortgage strategy built around your lifestyle and long-term goals.
Financing for eligible personal-use second homes
Conventional and jumbo options
Available for eligible purchases and refinances
Occupancy, personal use, rental activity, property type, down payment, reserves, and lender requirements apply.
YOUR ESCAPE · YOUR RETREAT
A Second-Home Strategy Built Around Lifestyle and Long-Term Planning
A vacation or second home is generally purchased for the borrower’s personal use in addition to a primary residence. Financing requirements can differ from a primary-home purchase, particularly when it comes to occupancy, reserves, down payment, property type, and intended rental activity.
Golden Oak Mortgage Group compares multiple lending partners to help qualified buyers review conventional, jumbo, fixed-rate, and other eligible second-home financing structures.
WHEN SECOND-HOME FINANCING MAY FIT
Is a Vacation Home Loan Right for You?
Personal-Use Second Home
Purchase an eligible property intended primarily for your own seasonal, vacation, or part-time use.
Favorite Destination
Explore financing for eligible beach homes, lake houses, mountain cabins, resort properties, or golf-course residences.
Create Lasting Memories
Build a place for family vacations, holidays, and meaningful time away from your primary residence.
Plan for the Future
Purchase a property you may enjoy now and potentially use more frequently later in life.
Flexible Financing Options
Compare conventional, jumbo, fixed-rate, and other eligible second-home mortgage structures.
Advisor-Guided Strategy
Review occupancy, rental plans, reserves, down payment, and lender requirements before making an offer.
WHAT LENDERS REVIEW
Clarify How the Property Will Be Used
The distinction between a second home and an investment property matters. Lenders review personal use, rental activity, location, property type, and the borrower’s overall financial profile before determining the appropriate program.
How often the borrower expects to occupy the property and whether it is genuinely a second residence.
Whether the property will be rented, placed in a rental pool, or operated primarily to generate income.
Property type, marketability, distance, resort characteristics, condominium eligibility, and appraisal considerations.
Available funds for closing plus any required post-closing liquidity or reserves.
Rate type, points, lender credits, term, monthly payment, and total cash needed.
PLAN YOUR SCENARIO
Helpful Second-Home Calculators
Estimate the payment, affordability, closing costs, and financing tradeoffs before reviewing the complete scenario with a Golden Oak mortgage advisor.
COMMON QUESTIONS
Vacation & Second Home Loan FAQs
What is a vacation or second-home loan?
It is a mortgage used to finance an eligible property that the borrower intends to occupy for part of the year in addition to a primary residence.
How is a second home different from an investment property?
A second home is generally acquired primarily for the borrower’s personal use. An investment property is generally acquired primarily to produce rental income or investment returns. Financing standards differ.
Can a vacation home be rented?
Limited rental activity may be permitted under some programs, but regular or primary income-producing use may require investment-property financing. The intended use should be reviewed before application.
How much down payment may be required?
Requirements vary by lender, loan amount, occupancy, property type, credit profile, reserves, and selected program. Second-home financing often requires more than a primary-residence transaction.
Can conventional financing be used?
Yes. Conventional financing is commonly used for eligible second homes. Qualified borrowers may also have access to jumbo or other lender-specific programs.
Can a luxury vacation home use jumbo financing?
Yes. Jumbo financing may be available when the required loan amount exceeds applicable conforming limits or the selected program otherwise requires a jumbo structure.
Can I finance a second home in another state?
Potentially, yes. Availability depends on property location, licensing, lender coverage, borrower qualifications, and the selected program.
What property types may qualify?
Eligible properties may include single-family homes, townhomes, certain condominiums, resort-area properties, lake houses, beach homes, mountain cabins, and new construction, subject to lender requirements.
Are rates different for second homes?
Pricing can differ from primary-residence financing because occupancy affects risk and program structure. Rate, points, lender credits, and requirements vary by lender and borrower profile.
Can I refinance a vacation home?
Eligible second homes may qualify for rate-and-term or cash-out refinancing, subject to loan-to-value, credit, reserves, property, and lender guidelines.
Can projected rental income be used to qualify?
That depends on whether the property is being treated as a second home or an investment property and on the lender’s documentation requirements. The intended use must be evaluated first.
Why compare multiple lenders?
Second-home guidelines can vary materially between lenders, especially for reserves, condominium eligibility, rental use, jumbo amounts, and property types.
READY TO PLAN YOUR GETAWAY?
We Can Help
Compare occupancy requirements, down payment, reserves, estimated payment, closing costs, conventional and jumbo options, and lender guidelines with a Golden Oak mortgage advisor.
This page is provided for general informational purposes and is not a commitment to lend or a determination that a property qualifies as a second home. All loans are subject to application, underwriting, credit approval, occupancy review, property review, appraisal, program requirements, and lender availability. Down payment, reserve, rental-use, property-type, pricing, and documentation requirements vary by lender and may change without notice.