
HIGH-VALUE HOME FINANCING
Jumbo Home Loans
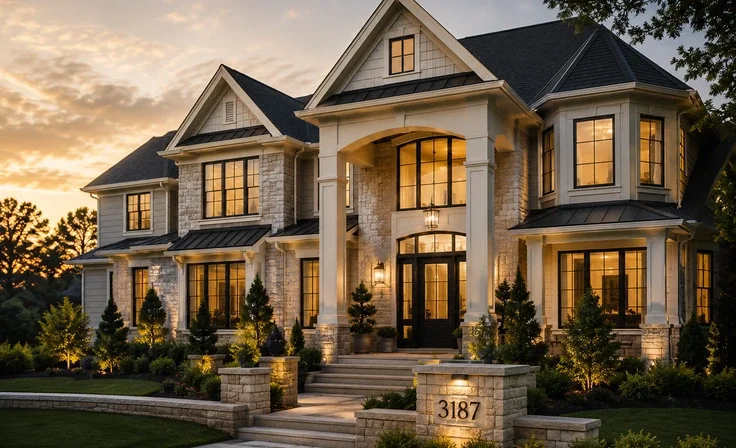
Explore mortgage options for luxury homes, custom residences, waterfront properties, and other high-value real estate when your financing needs exceed conforming loan limits.
Higher eligible loan amounts
Multiple lender and documentation options
Available for eligible purchases and refinances
Loan limits, documentation, reserves, and property requirements vary by lender and program.
LUXURY FINANCING · TAILORED SOLUTIONS
A Jumbo Strategy Built Around the Full Financial Picture
Jumbo loans provide financing for mortgage amounts above applicable conforming limits. They are frequently used for luxury homes, custom properties, high-cost markets, second homes, and other eligible high-value real estate.
Because jumbo underwriting standards vary widely, Golden Oak Mortgage Group compares multiple lending partners to evaluate loan amount, rate structure, points, reserves, documentation, property eligibility, and overall financing fit.
WHEN JUMBO FINANCING MAY FIT
Is a Jumbo Loan the Right Fit?
Luxury Home Financing
Designed for eligible buyers purchasing homes that exceed applicable conforming loan limits.
Strong Financial Profile
Jumbo programs commonly evaluate income, assets, credit, reserves, and the overall strength of the borrower profile.
Higher Loan Amounts
Access financing structures created for larger mortgage amounts and premium real estate.
Flexible Mortgage Options
Compare fixed-rate, adjustable-rate, and specialty jumbo programs offered by multiple lending partners.
Broader Property Goals
Finance eligible primary residences, second homes, vacation properties, and select investment opportunities.
Personalized Lending Strategy
Review lender guidelines, pricing, reserves, and documentation requirements with a Golden Oak mortgage advisor.
WHAT JUMBO LENDERS REVIEW
Prepare for a More Detailed Financial Review
Higher loan amounts can involve more detailed underwriting. Preparing the full financial picture early may help identify the strongest available lender and program options.
Employment, business income, tax returns, bonus income, and other qualifying earnings.
Funds needed for closing plus required post-closing liquidity or reserves.
Credit history, score, liabilities, payment obligations, and overall risk profile.
Property type, marketability, value, condition, and appraisal requirements.
Occupancy, down payment, term, rate type, points, and lender-credit strategy.
PLAN YOUR SCENARIO
Helpful Jumbo Mortgage Calculators
Model the payment, cash needed, and jumbo-versus-conforming comparison before reviewing the complete scenario with a mortgage advisor.
COMMON QUESTIONS
Jumbo Mortgage FAQs
What is a jumbo loan?
A jumbo loan is a mortgage with a loan amount above the applicable conforming loan limit. Jumbo loans are not eligible for purchase by Fannie Mae or Freddie Mac under standard conforming guidelines.
When might a borrower need jumbo financing?
Jumbo financing may be appropriate when the required mortgage amount exceeds the conforming limit for the property’s location or when a higher-value property requires a larger loan structure.
Do jumbo loan limits vary by location?
Yes. Conforming loan limits are established annually and may differ in designated high-cost areas. A loan becomes jumbo when it exceeds the applicable conforming limit for the property.
What credit profile is typically needed?
Requirements vary significantly by lender and program. Stronger credit profiles may provide access to more favorable pricing, larger loan amounts, or more flexible terms.
How much down payment is required?
Down-payment requirements depend on loan amount, occupancy, property type, credit, reserves, and the selected lender program. Qualified borrowers may have access to multiple structures.
Are reserves commonly required?
Many jumbo programs require borrowers to document post-closing reserves. The amount may depend on loan size, number of financed properties, occupancy, and overall borrower profile.
Can self-employed borrowers qualify?
Yes. Jumbo lenders may offer full-documentation, bank-statement, asset-based, and other eligible documentation programs for qualified self-employed borrowers.
Can jumbo financing be used for a refinance?
Jumbo financing may be available for eligible rate-and-term refinances, cash-out transactions, term changes, or refinancing an existing jumbo mortgage.
Are jumbo rates always higher than conforming rates?
No. Jumbo pricing depends on market conditions, loan size, borrower qualifications, property type, lender appetite, and the selected rate-and-fee structure.
Why compare multiple jumbo lenders?
Jumbo underwriting standards and pricing can vary substantially between lenders. Comparing multiple programs may reveal meaningful differences in loan amount, reserves, documentation, rate, points, and eligible property types.
READY TO EXPLORE YOUR OPTIONS?
We Can Help
Compare lender guidelines, estimated payment, down payment, reserves, documentation, rate structures, and eligible loan amounts with a Golden Oak mortgage advisor.
This page is provided for general informational purposes and is not a commitment to lend. All loans are subject to application, underwriting, credit approval, property review, appraisal, program requirements, and lender availability. Jumbo loan limits, pricing, documentation, reserve requirements, eligible property types, and underwriting guidelines vary by lender and may change without notice.